Is a 72-Month Car Loan a Good Idea?
A 72-month car loan is usually not a good idea unless the payment on a shorter loan truly doesn't fit your budget. The longer term lowers your monthly payment, but you pay more total interest and you stay at risk of owing more than the car is worth for years longer. Here's how to decide.
What does a 72-month car loan actually cost?
The same car costs more the longer you take to pay for it. This example is our own math, not a quote: a $25,000 loan at 8% APR, with no down payment and no fees.
- 48 months: about $610 a month, about $4,296 in interest
- 60 months: about $507 a month, about $5,415 in interest
- 72 months: about $438 a month, about $6,560 in interest
- 84 months: about $390 a month, about $7,731 in interest
Going from 48 to 72 months cuts the payment by roughly $172 a month, but adds about $2,264 in interest. Your rate will differ, and rates often run higher on longer terms, so run your own numbers before you commit.
Why is a long loan riskier?
Cars lose value fastest in the first few years. On a long loan you pay down the balance slowly, so for a while you can owe more than the car is worth. That's called negative equity. It matters if the car is totaled, or if you want to trade it in before the loan ends. Our guide on trading in a car that still has a loan explains what happens in that spot.
A long term also outlasts many warranties. You could be making payments on a car that's out of coverage and needs repairs.
When can a 72-month loan make sense?
A longer term can be reasonable when:
- You're putting a solid down payment on the car, so you start with equity.
- The car is known for lasting well past the loan, and you plan to keep it that long.
- The shorter payment is the only way to afford a safe, reliable car, and you have room to pay extra when you can.
If you take a longer loan, check that it has no prepayment penalty, so you can pay it off early without a fee.
How do you choose a loan term you can live with?
Start with what you can afford, not the payment a salesperson quotes. Our post on how much car you can actually afford walks through a budget rule of thumb. Then try these steps:
- Pick the shortest term whose payment fits your budget comfortably.
- Put more down if you can. See how much down payment you need for a used car.
- Choose a less expensive car instead of stretching the term to fit a pricier one.
- Get pre-qualified first so you know your real rate. A pre-qualification usually uses a soft credit check, covered in our pre-qualification guide.
Ready to compare cars at different prices? Browse used cars on Keysy and see what fits a shorter loan.
FAQ
Is 72 months too long for a used car loan? Often, yes. Used cars have fewer years of warranty left, so a long loan can outlast your coverage. Many buyers do better with 36 to 60 months.
Does a longer loan hurt my credit? The term itself doesn't lower your score. Late payments do, and a stretched budget makes them more likely.
Can I pay off a 72-month loan early? Usually, but confirm the loan has no prepayment penalty before you sign.
Will a longer term get me a lower rate? Not usually. Lenders often charge higher rates on longer terms, so ask for quotes at several lengths.
What's the best loan length? The shortest one with a payment you can carry comfortably. For help with credit and approvals, see our used car financing in Utah page.
More from Keysy Resources
How Much Down Payment Do You Need for a Used Car?
There's no universal minimum down payment on a used car. Many buyers aim for 10% to 20% because it lowers the payment and protects against owing more than the car is worth. Here's how to choose your number.
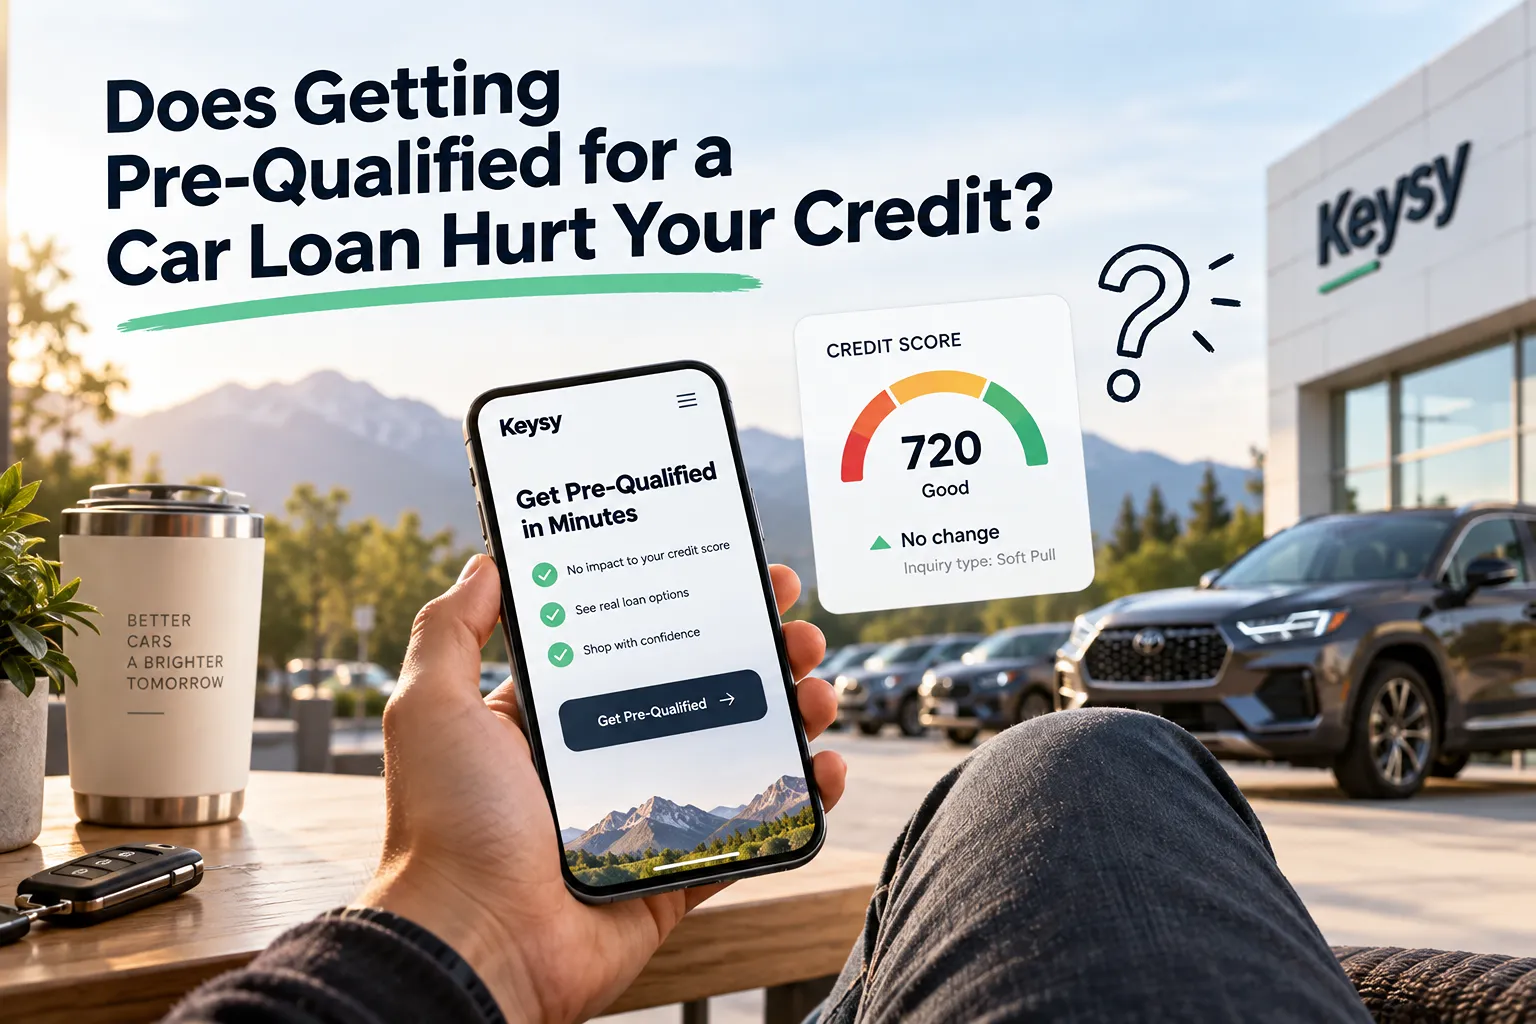
Does Getting Pre-Qualified for a Car Loan Hurt Your Credit?
Pre-qualifying for a car loan usually uses a soft credit check, which doesn't affect your score. Here's how it differs from a hard inquiry, and when a hard one happens.
How Much Car Can I Actually Afford?
Lenders will approve you for more than you should borrow. Here's how to find the number that actually fits your budget.