Does Getting Pre-Qualified for a Car Loan Hurt Your Credit?
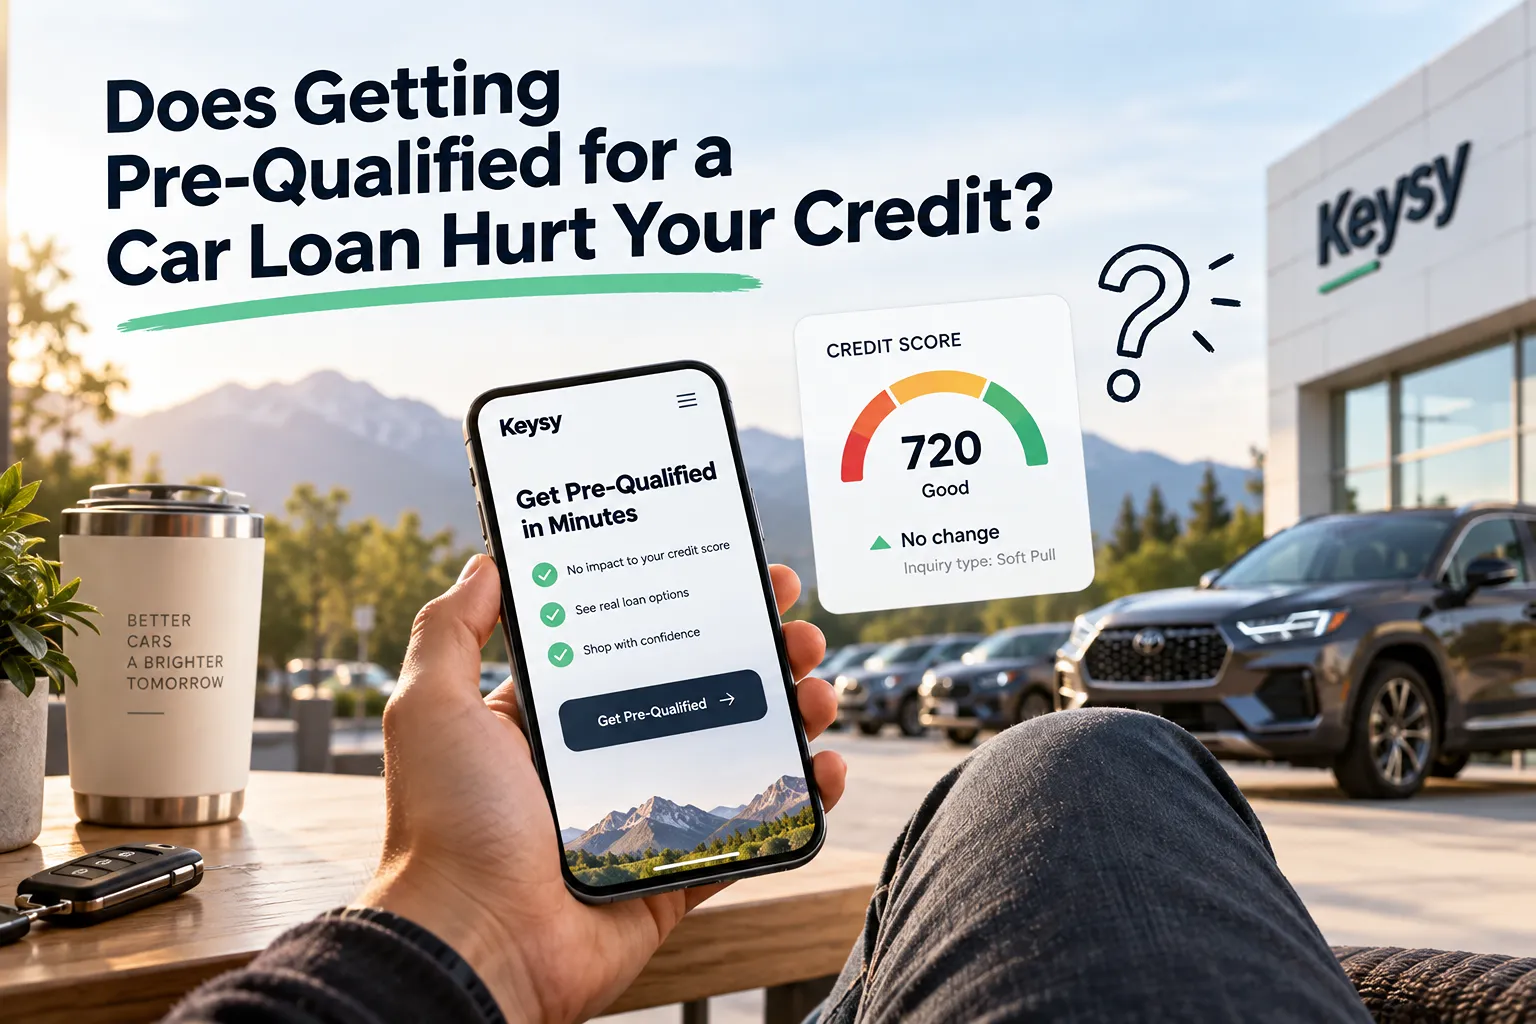
No. Getting pre-qualified for a car loan usually uses a soft credit check, and a soft check doesn't lower your credit score. A hard inquiry can, but it typically happens later, when you formally apply for a specific loan.
The difference is worth knowing before you shop, because it decides whether you can look at real numbers without paying for it in points.
What's the difference between a soft and a hard credit check?
Both pull information from your credit report. The difference is why they happen and whether they affect your score.
- Soft inquiry: A check that isn't tied to a credit application. Checking your own credit and pre-qualification offers are examples. It doesn't affect your score, and lenders can't see it.
- Hard inquiry: A check a lender makes when you apply for credit. It can lower your score by a few points, and it stays on your report for two years.
According to FICO, a single hard inquiry typically takes off fewer than five points for most people. Your score usually recovers within a few months if you keep paying on time.
Does pre-qualifying hurt my credit?
Pre-qualification is designed to be a preview. A lender looks at your credit profile and tells you the range of rates and terms you're likely to get. Because you haven't applied yet, most lenders use a soft pull.
Check how a lender describes it before you start. If the form says it will run a "hard inquiry" or "hard pull," that's an application, not a preview.
When does a hard inquiry happen?
A hard inquiry happens when you accept a loan offer and a lender needs to make a final approval decision. That's the point where the lender is taking on real risk, so it reviews your full credit file.
You may also see one if you apply directly with a bank or credit union, or if you finance through a dealership that sends your application to several lenders.
What if I compare rates from several lenders?
Shopping around for an auto loan doesn't have to cost you several separate hits. Scoring models like FICO treat multiple auto loan inquiries made within a short window as a single inquiry. The window is 14 days in older FICO versions and up to 45 days in newer ones, so keep your applications close together.
The safe approach is to do your rate shopping in one stretch of a week or two, not spread across a month.
How does this work when you buy a car on Keysy?
When you build a deal on Keysy and choose to finance through the platform, you see a real estimate of your rate range before you sign anything. Keysy gets that estimate from a soft credit pull, so viewing your numbers doesn't affect your score.
That means you can adjust your down payment, term, and monthly payment against real numbers, not a guess. You can also bring your own bank or credit union financing if you already have a rate you like. For the full flow from shopping to signing, read Can You Really Buy a Car Completely Online?
If you're still working out what payment fits your budget, How Much Car Can I Actually Afford? walks through it. To see what's in stock, browse cars on Keysy.
Does my credit score change what I'm offered?
Yes. Your score shapes your interest rate and how much lenders will approve. Knowing your range early helps you set a realistic budget. For the tiers lenders use, see What Credit Score Do You Need to Buy a Car? If you're in Utah, used car financing in Utah covers local options.
Frequently asked questions
Does checking my own credit score hurt it? No. Checking your own credit is a soft inquiry and doesn't change your score.
Can a dealer run my credit without asking? A lender needs your permission to run a hard inquiry. A dealer or platform should tell you before it pulls your credit, and should say whether the pull is soft or hard.
How long does a hard inquiry stay on my report? Two years. FICO counts it toward your score for the first 12 months.
Will several car loan applications hurt more than one? Not if you make them within the same short window. Scoring models generally treat auto loan inquiries in that window as one.
Is pre-qualification the same as approval? No. Pre-qualification is an estimate. Final approval depends on the full application, the vehicle, and the loan amount.
More from Keysy Resources
Is a 72-Month Car Loan a Good Idea?
A 72-month car loan lowers your monthly payment, but you pay more interest and stay underwater longer. Here's the math on loan length and how to pick a term you can live with.
How Much Down Payment Do You Need for a Used Car?
There's no universal minimum down payment on a used car. Many buyers aim for 10% to 20% because it lowers the payment and protects against owing more than the car is worth. Here's how to choose your number.
How Much Car Can I Actually Afford?
Lenders will approve you for more than you should borrow. Here's how to find the number that actually fits your budget.