Should You Get Car Financing From the Dealer or Your Bank?
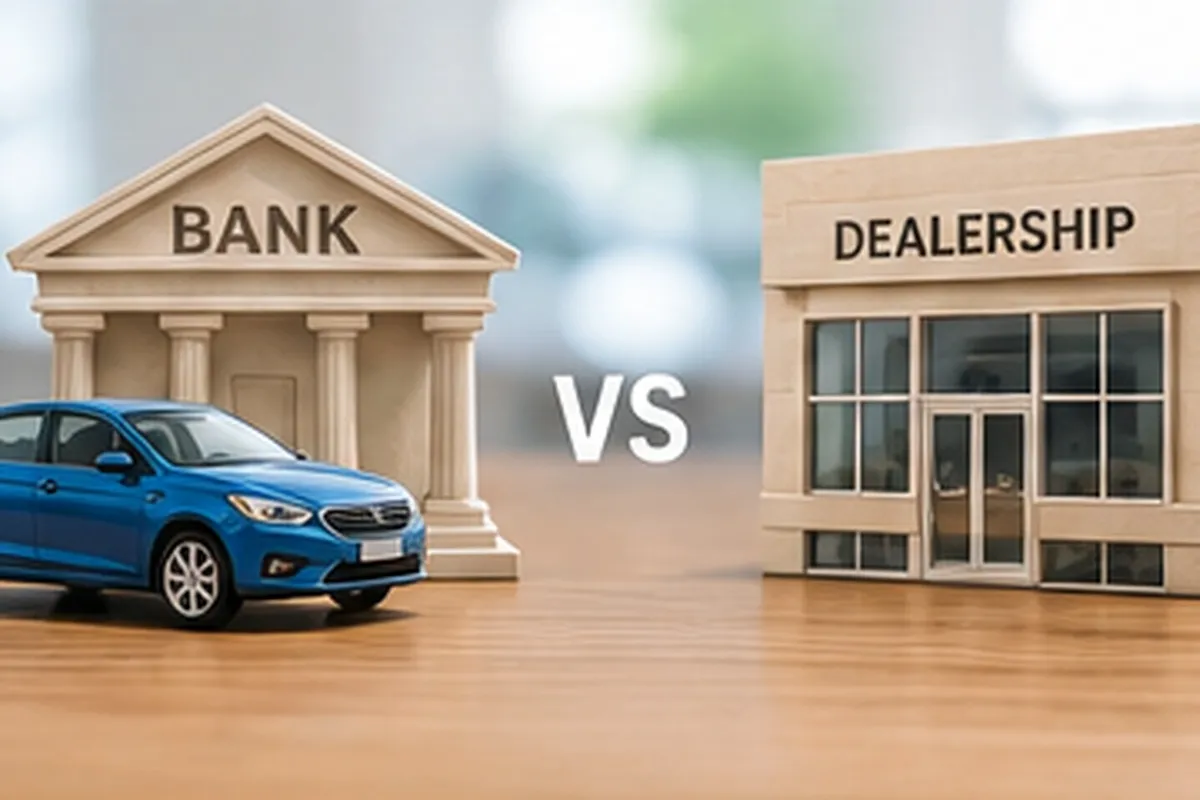
Should you get car financing from the dealer or your bank? Neither is always cheaper, so the best approach is to get both offers and compare them. Bring a pre-approval from a bank or credit union, then let the dealer try to beat it. You keep whichever has the lower total cost.
What's the difference between dealer financing and a bank loan?
With a bank or credit union loan, you borrow directly from the lender and then shop for a car with that money in hand. With dealer financing, the dealership sends your application to one or more lenders it works with and presents you with an offer. The lender still makes the loan. The dealer is the go-between.
Because the dealer can ask several lenders at once, it sometimes finds a lower rate than you'd get on your own. The dealer may also be paid for arranging the loan, which can show up as a higher rate than the lender would have offered you directly. That's why a competing offer matters.
Why get pre-approved before you shop?
A pre-approval tells you what rate and loan amount a lender will offer before you walk into a negotiation. It gives you a benchmark. If the dealer's offer is better, you take it. If it's not, you already have a good one in your pocket.
Many lenders pre-qualify you with a soft credit check, which doesn't affect your score. A formal application usually involves a hard inquiry. Ask which one you're getting before you apply.
When does dealer financing make sense?
- It beats your outside offer. If the dealer matches or undercuts your pre-approval, there's no reason to say no.
- You want one stop. Financing, trade-in, and signing in one place is simpler, especially when you buy online.
- Your credit is still building. Dealers often work with a wider range of lenders, which can help when your own bank says no.
- Manufacturer or special offers apply. Some new and certified cars come with promotional rates you can only get through the dealer.
When does a bank or credit union loan make sense?
- You already have a relationship. Credit unions in particular often offer competitive rates to members.
- You want to separate the two decisions. Settling the loan first lets you negotiate the car price without mixing in the financing.
- You want a firm budget. A pre-approval caps what you can borrow, which keeps you from stretching.
How do you compare two loan offers?
Don't compare monthly payments alone. A lower payment can just mean a longer loan. Line the offers up on these points:
- APR. The annual percentage rate includes interest and most lender fees, so it's the fairest side-by-side number.
- Loan term. A longer term lowers the payment but raises the total interest you pay.
- Total cost. Multiply the payment by the number of months and add any down payment. The lower total wins.
- Fees and add-ons. Check for origination fees, prepayment penalties, and optional products rolled into the loan.
Ask for each offer in writing with the same loan amount and term, so you're comparing like with like.
Can you switch financing after you buy?
Often, yes. You can refinance later with another lender if rates or your credit improve. Check your contract for any prepayment penalty first. It's still easier to start with a good loan than to fix a poor one later.
How does this work when you buy online?
Buying online follows the same logic. You can apply for financing from home, see your terms before you commit, and e-sign the paperwork. If you already have an outside offer, bring it along and compare. You can read more about used car financing in Utah, or browse used cars on Keysy to see what fits your budget.
FAQ
Is dealer financing more expensive than a bank loan?
Not always. Sometimes the dealer finds a lower rate, and sometimes the rate is marked up. Getting an outside offer first lets you check.
Does it hurt my credit to shop for a loan?
Pre-qualification usually uses a soft check that doesn't affect your score. Formal applications can involve a hard inquiry, so ask first.
Do I have to use the financing I'm pre-approved for?
No. A pre-approval is an offer, not a commitment. You can take a better one if the dealer finds it.
Should I tell the dealer I have a pre-approval?
Yes, once you're ready to talk financing. It shows the number they need to beat.
What's more important, the rate or the monthly payment?
Look at the APR and the total cost. A low payment on a long loan can cost you more overall.
More from Keysy Resources
Can You Buy a Car With a Cosigner? How It Works and What It Risks
Buying a car with a cosigner can help you qualify, but both signers take on repayment risk. Learn how it works and what to discuss before signing.
What Is the Difference Between APR and Interest Rate on a Car Loan?
The interest rate is the cost of borrowing. The APR adds certain lender fees to it, which makes APR the better number for comparing car loans. Here's what each covers and what to ask before you sign.
Should You Refinance Your Car Loan? When It Saves Money and When It Doesn't
Refinancing a car loan can lower your APR or payment, but only in the right situation. Here's when it saves money, when it doesn't, and how to compare offers.